US Mortgage Rates Near 7% Put More Homebuyers on Hold as Affordability Shrinks
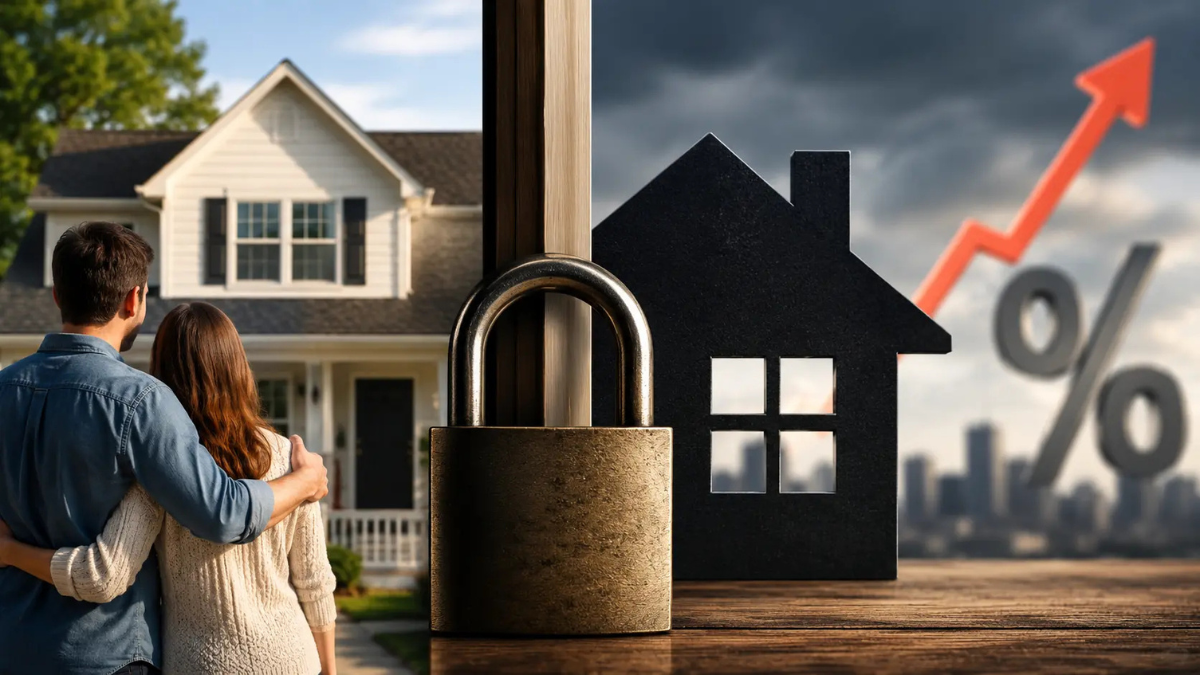
United States | September 18, 2026: The cost of buying a home in the U.S. is rising again as mortgage rates move closer to the 7% mark, putting additional pressure on buyers already dealing with high home prices and limited housing supply. Higher borrowing costs are reducing purchasing power and could keep more prospective buyers on the sidelines.
Freddie Mac's weekly average for a 30-year fixed-rate mortgage reached 6.76% last week, its highest level in more than 14 months. Other mortgage trackers have already reported rates around or slightly above 7%, highlighting the growing affordability challenge for home shoppers.
Why Mortgage Rates Are Moving Toward 7%
Mortgage rates have been climbing for months as inflation expectations and higher oil prices have pushed long-term bond yields higher.
The 30-year mortgage rate generally moves in relation to the 10-year U.S. Treasury yield, which rose from 3.97% in late February to above 5% this week for the first time since 2023.
That means mortgage rates can rise even when the Federal Reserve is not directly changing mortgage rates.
What the Federal Reserve Rate Hike Means
The Federal Reserve raised its key interest rate on Wednesday, its first increase in three years, as policymakers responded to rising inflation.
The Fed does not directly determine 30-year mortgage rates. However, its decisions influence bond-market expectations, which can affect Treasury yields and, in turn, mortgage pricing.
The central bank also indicated that another rate increase could be possible later this year.
For homebuyers, the combination of elevated Treasury yields and tighter monetary policy creates uncertainty over when borrowing costs may become meaningfully cheaper.
Higher Rates Are Cutting Homebuying Power
A mortgage rate near 7% can substantially increase the monthly cost of financing a home compared with the ultra-low rates available during the pandemic.
As monthly payments rise, buyers may have to:
- Reduce their target home price
- Increase their down payment
- Delay purchasing
- Look in less expensive locations
- Accept a larger share of their income going toward housing costs
The impact varies by borrower because mortgage rates also depend on income, credit profile, loan terms and other factors.
Home Prices and Housing Shortages Add to the Pressure
Higher mortgage rates are hitting a market that was already facing affordability problems.
U.S. home prices rose sharply during the early part of the decade, while years of below-average home construction contributed to a persistent shortage of housing.
The result is a difficult combination for buyers: expensive homes plus expensive financing.
For households that are already close to their maximum affordable monthly payment, even a relatively small increase in mortgage rates can change the type of property they can realistically purchase.
Why Buyers Are Delaying Their Home Search
Many prospective buyers are watching mortgage rates closely in the hope that lower borrowing costs will eventually improve affordability.
But waiting also carries uncertainty.
If mortgage rates remain elevated, buyers could continue postponing purchases. If rates fall later, more buyers could return to the market at the same time, potentially increasing competition for available homes.
The current environment is therefore forcing buyers to weigh the cost of waiting against the cost of purchasing at today's financing rates.
US Home Sales Are Already Under Pressure
The U.S. housing market has struggled since mortgage rates began moving higher in 2022.
Sales of previously owned homes were essentially flat last year at a 30-year low, and existing-home sales slowed again last month.
Higher borrowing costs could add another obstacle to a market already dealing with affordability constraints and limited inventory.
What Homebuyers Should Check Now
Buyers considering a purchase should focus on the total monthly housing cost, rather than looking only at the headline mortgage rate.
Before making an offer, buyers can compare different loan scenarios, evaluate how a rate change affects their monthly payment and avoid stretching their budget simply to enter the market.
It is also important to remember that the advertised average mortgage rate is not necessarily the rate every borrower will receive.
What Happens Next
The direction of mortgage rates will depend on inflation, Treasury yields, Federal Reserve policy and broader economic expectations.
With rates already approaching 7%, affordability is likely to remain a major constraint for U.S. homebuyers in the near term.
The bigger question for the housing market is whether borrowing costs stabilise or move higher from here. Either outcome will matter for buyers who are already delaying purchases because current monthly payments remain too high.