Phoenix Mills Q2: Profit Up 11% to Rs 427 Crore, EBITDA Margin 62%
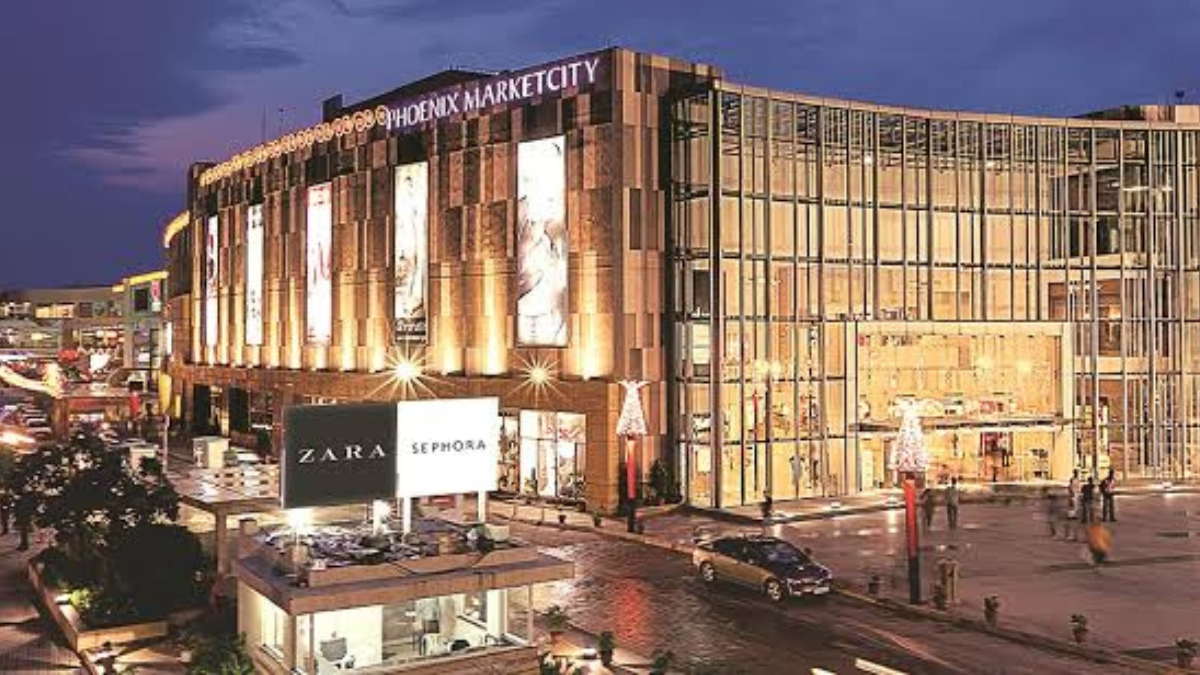
Phoenix Mills reported a consolidated net profit of Rs 427 crore for July-September 2026, up 11.2% from Rs 384 crore a year earlier. The results were announced on Friday, October 30.
What are the key numbers?
-
Total revenue: Rs 1,152.81 crore, up 3.4% from Rs 1,115.43 crore
-
EBITDA: Rs 710 crore, against Rs 670 crore, with a margin of about 61.6%
-
Profit before tax: Rs 549.64 crore, against Rs 514.54 crore
-
Property and related services: segment revenue up about 16%
How does it compare with expectations?
HDFC Securities' preview had forecast revenue of about Rs 1,129 crore and EBITDA of about Rs 703 crore, so the quarter came in broadly in line. Net profit margin works out to about 37% (our calculation).
Why is the margin so high?
Phoenix Mills earns most of its income from rent and related charges on malls it owns, which carry far higher margins than selling apartments. Analysts note the company is moving away from one-time residential sales towards recurring rental income.
What does it tell us about consumption?
Higher mall income points to steady retail demand in the festive run-up, though total revenue grew only about 3%, so this was a quarter of margin and mix more than of volume. Anarock's Anuj Puri had flagged possible near-term caution in retail after the RBI's rate hike and softer festive spending.
What to watch
How the company's new malls ramp up and whether festive-quarter trading holds. Rating changes are one opinion, not advice.