US Builders Bring Back 4% Mortgages as Home Prices Face Growing Pressure
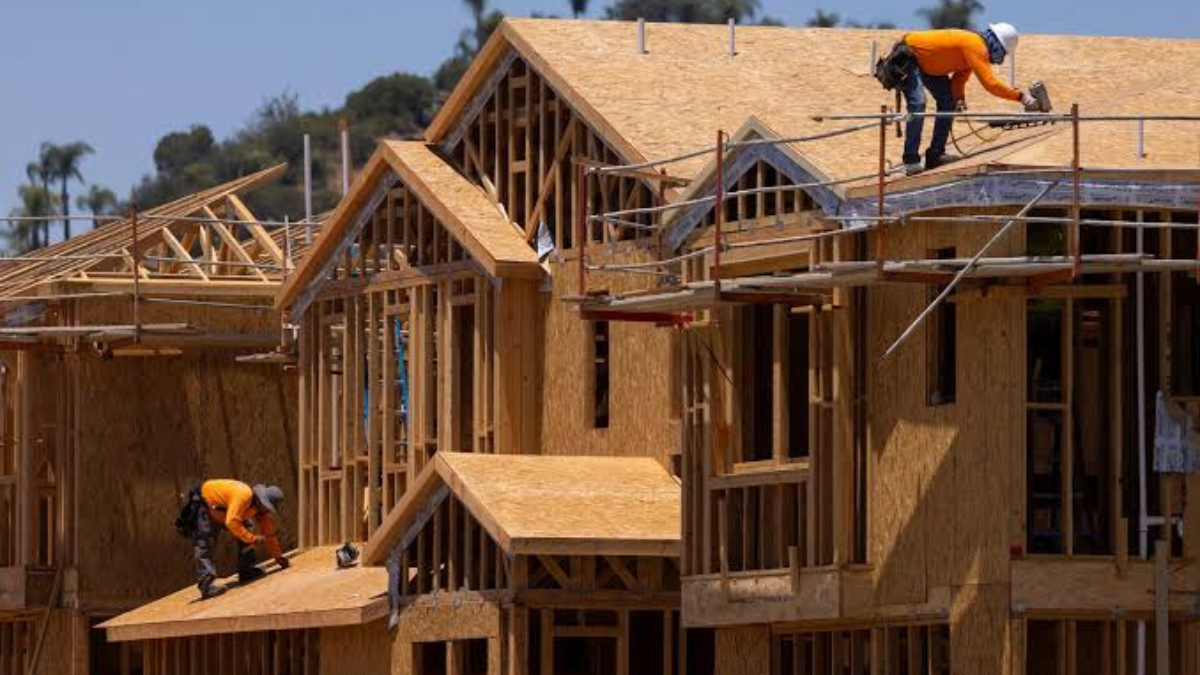
New York, USA | September 16, 2026: US homebuilders are increasingly using mortgage-rate incentives to make new homes affordable without cutting asking prices, creating a new calculation for buyers. With advertised rates falling below 4% on a growing share of new-construction listings, buyers can reduce monthly payments significantly — but the strategy could also keep new-home prices higher and leave some owners with larger mortgage balances.
Builders Are Cutting Mortgage Payments Instead of Home Prices
Nearly 1 in 7 new-construction listings advertised a reduced mortgage rate in August, with the average promotional rate at just 3.92%, according to Realtor.com analysis.
That compares with a market 30-year fixed mortgage rate of around 6.67% during the period.
On a $450,000 new home with 20% down, the lower rate can reduce monthly principal and interest payments by roughly $614, or nearly $7,400 annually.
The strategy is becoming particularly common in higher-priced new homes. Reduced-rate incentives appeared on 17.1% of homes priced between $500,000 and $750,000, compared with just 1.4% of homes priced between $100,000 and $200,000.
For move-up buyers, the incentive may also help offset the reluctance to give up an existing low-rate mortgage.
Why Buyers Are Seeing 4% Financing but Not Bigger Price Cuts
The broader US housing market is showing signs of affordability pressure. Median list prices fell 1.3% year over year in August, marking the 10th consecutive annual decline, while 20.4% of listings had a price reduction.
Yet builders have another way to compete: subsidising the buyer's mortgage instead of reducing the property's sticker price.
An American Enterprise Institute Housing Center analysis estimated that cutting a mortgage rate by one percentage point costs a builder roughly 3.2% of the home's sale price. Delivering a similar monthly-payment reduction through a price cut could require a much larger reduction of about 10%.
That makes rate buydowns financially attractive for builders trying to protect headline prices while making monthly payments more manageable.
The Catch for New-Home Buyers
The lower payment does not necessarily mean the buyer is purchasing a cheaper property.
If a buyer uses the lower interest rate to maintain the same monthly payment, the financing incentive can support a significantly larger loan. That means the homeowner could carry a higher outstanding balance even though the monthly payment initially looks more affordable.
This becomes a potential concern if property values subsequently decline.
Freddie Mac has also cautioned that appraisers need to account for financing concessions when analysing comparable sales because builder incentives can influence transaction prices.
What Buyers Should Check Before Taking a Builder Incentive
A 4% mortgage can provide meaningful short-term savings, but buyers should look beyond the advertised rate.
Before purchasing, buyers should compare:
- The home's price with similar resale and new-build properties
- The promotional rate and how long it lasts
- The permanent rate after any temporary buydown period
- Builder incentives versus an equivalent price reduction
- Expected resale value if the incentive disappears
- The remaining mortgage balance under different market scenarios
What Happens Next for US New Homes
Builder incentives are likely to remain an important tool while mortgage rates stay elevated and buyers remain sensitive to monthly payments.
The key question for the housing market is whether these incentives are simply improving affordability or also preventing new-home prices from adjusting further.
For buyers, the distinction matters. A lower mortgage payment can make a home easier to afford today, but it does not automatically make the underlying property cheaper.